April is the month our industry remembers, celebrates, and recommits to Fair Housing.
Fair housing is more than a list of dos and don’ts, rights and penalties, and mandatory continuing education.
As stewards of the right to own, use and transfer private property, fair housing depends on a free, open market that embraces equal opportunity.
Join me in recognizing the significance of the Fair Housing Act and reconfirm a commitment to upholding fair housing law as well as a commitment to offering equal professional service to all in their search for real property.
The predictions of the real estate market have been about as accurate as the local weather forecast in areas without Doppler Radar.
Two headlines in real estate, really?!
Yes.
The summary? Solid demand with low inventory means fewer options for real estate buyers AND a tale of two markets.
In a recent WSJ article, Nicole Friedman wrote the United States is a country of two housing markets. In one, home prices are falling from a year ago. In the other, they’re still posting annual gains. That division runs right down the center of the U.S. She listed – with data from Black Knight – the top 10 markets with the largest price increases between February 2020 and January 2023:
Tampa up 59%
Miami up 53%
Austin, Texas, up 50%
Jacksonville up 50%
Charlotte up 49%
Atlanta up 49%
Nashville up 48%
Orlando up 48%
Raleigh up 47%
Phoenix up 47%
Nicole’s article points out that real estate markets are hyper-local and geography-specific. According to Michael Simonsen from Altos Research, we continue to see a seller’s market across the US. You can see the National numbers – on this link – and type in your own zip code for a local view.
In looking at this week’s Altos data, the top 10 markets with the most listings absorbed – it’s a Texas sweep:
Houston
San Antonio
Fort Worth (Does Fort Worth Ever Cross Your Mind?)
Austin
Dallas
Orlando
El Paso
Denver
Minneapolis
Lubbock (Buddy Holly and Mac Davis would like this)
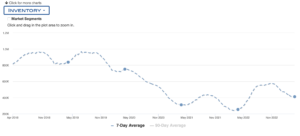
I observed this week on a National basis another 1% drop in inventory for sale at a time when inventory is typically rising by 1% or more each week. This, in my view, is a leading indicator of a supply-constrained market for the Spring buying season. Many homeowners have a current mortgage rate below 4%, and many don’t want to sell their current rate and pay a higher rate for a different house.
Implication? It’s going to be a great time for remodeling contractors.
Many homeowners are also sitting on large cushions of equity, and the institutional investors show no sign of liquidating inventory, which is likely to prevent any big wave of foreclosures and distressed sales.
Inventory For Sale In The US. Source Altos Research for the week ending 4/2/23
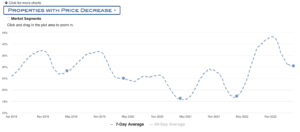
In many markets across the US, housing demand is high enough for sellers to command pricing. In fact, the latest percentage of listed homes with a price decline dropped this week to 30.5% when just a month ago, it was nearly 40%. Investors and buyers who were sitting on the fence missed an opportunity back in November and December.
Listed Real Estate Properties With A Price Decrease. Source Altos Research for the week ending 4/2/23
In other news, according to Altos, the median price of a new listing his week rose to $437,500 across the US, while the median rent was $2,250. The headlines will be hard to interpret as some are comparing to last year’s unprecedented price increases. The data shows increasing prices on a National basis but not near the pace of last year. My view? The unprecedented rise in mortgage rates has softened demand but not enough to balance the market.
The solution? Building, renovation, and conversation of mall and unused office space for residential use. The issue, according to Nicole, is Home builders have been hampered by supply-chain issues and labor shortages. Yet, Jonathan Lanser, a real estate and business journalist for the Orange County Register, recently reported that new home builders gained 2.8% in market share. Yet is it enough? I say no. It seems to me from a National, Regional, and local City perspective, we need to address housing policy to place this vital sector of the US economy in a position to enable the American dream vs. destroying it.
Jennifer Love Hewitt turns 44, and Corbin Blue 34. The job market is booming. Inflation is falling. Yet, if you asked your neighbor, the news about eggs and housing might get in the way… is it a real estate seller’s market?
Sellers are hard to find…
Active inventory for sale fell 1.5% this week
Nearly 6% fewer homes went pending this week
Mortgage rates ticked up to nearly 6.3% from 6.1%
The percentage of listings that have executed a price cut has dropped nearly 24%
Bottom line: buyers have fewer choices
Check out the latest stats in your area – click here – and if you need a local area expert, I know a few around the country.
Total Inventory For Sale In North Texas Dropped 5%
This blog was written for my North Texas audience, yet in the links below, you can check out the stats in your local area. The North Texas market consistently ranks as one of the top 5 real estate markets across the US.
Homebuyers are defying the real estate market in North Texas, and for real estate agents and brokers, this is a critical time to stay informed. For the week ending 2/10/2023, inventory for sale in the DFW MSA dropped nearly 5% while the median new list price remained flat. There is significantly more inventory for sale than we had just a year ago, and buyers are back in the market. The average days on the market range from 56 to 78 days, depending on the price range.
My view, along with the CEO of Altos Research, Michael Simonsen, is that buyers know if they buy now and rates drop, they can refinance in the future, or if rates tick up, they are in an excellent position.
On a national basis, we have record employment levels, and the North Texas area is expanding organically and with new businesses coming into the area. Thus, buyers can afford homes, and with the median rent in North Texas at nearly $2,300 per month, the rent vs. buy decision favors buying.
Looking at the current market as a demand-only equation could be a mistake. Before the pandemic period, a drop in inventory for sale in February was unusual, as historically, many sellers would list to get ahead of the spring market. Sellers are holding onto those 3% mortgages unless they have a compelling reason to move. Regardless, recently-listed properties with a price decrease have dropped from nearly 50% a month ago to 40% this month, indicating a strengthened market.
You can check out the DFW stats or your local city and zip; click here and if you can; participate in the Altos monthly webinar this Thursday, 2/16/2023, at noon central, register here. Topics will include:
– First signals of what Altos is seeing for 2023
– An update on home values and where this is likely headed
– What declining inventory means for the market
– The impact of interest rates and inflation
– How to talk to buyers and sellers about the data
Source: Altos Research DFW MSA for the week ending 2/10/2023
PS: Looking to increase your real estate team or office recruiting game? Book a demo to find out how we can 5X your ROI.
The acquisition of Realtor.com could boost competition, says Mark Johnson, Co-Founder of CoRecruit and former CEO of JPAR – Real Estate.
I recently had a call with Candace Evans, the Founder and Creator of CandysDirt.com, and she asked me if the CoStar and Move proposed acquisition was a big deal. My answer was yes! The rumor on the street – started at the Inman Connect Conference – is a possible acquisition price of $3 billion dollars, and that certainly is a big deal.
My business acquaintance and friend, Steve Murray, co-founder of REAL Trends, said, “I’m not convinced a sale would have a meaningful impact for real estate brokerages. These firms think if they control the information, they’ll control the distribution of buyers and sellers to agents and change the economics to where they’ll be getting a bigger share of the commission dollar. I suppose all those things are possible, but Zillow hasn’t been able to pull it off.”
Rupert Murdoch’s News Corporation purchased Move Inc. for nearly $1 billion in 2014, followed by the 2018 acquisition of the Austin, Texas-based lead-generation firm OpCity. CoStar has spent more than $2 billion on residential real estate deals over the last decade, beginning in 2014 with Apartments.com and later acquiring Homesnap in 2020 to launch Citysnap. CoStar’s market cap has more than doubled since 2018 to $32 billion, compared to Zillow’s $10 billion.
You never know the true motivations of sellers and buyers, yet for Move, it could be cashing out at the right time to focus on other aspects of the business, and it seems CoStar might be taking advantage of a strong cash position and difficult market conditions to make a strategic acquisition at a favorable price. CoStar understands the business and has a strong track record of adding value. A new owner always brings new ideas and new innovations, and that typically drives more competition. And competition always creates more favorable pricing for users. For agents, teams, and brokers, this could be really good news.
Across the industry, you are seeing major players acquire tools and technology to serve the consumer and the agent from the contemplation of a home sale or purchase all the way through to closing, funding, and post-sale support. So this will not be the last acquisition we hear about as the big players in the industry want to capture a larger share of more services within the nearly 5 million homes sold each year.