Staying On Top Of The Housing Market

Staying on top of the housing market is key to serving your clients. Here’s a quick snapshot of the latest trends that will impact your real estate practice:

  • Price Adjustments: Sellers are increasingly adjusting their expectations, with a notable uptick in price reductions from initial listings in the last few weeks.
  • Conditions Count: Homes that aren’t “move-in” ready are facing pressure in this competitive market.
  • Market Dynamics: A significant 34.4% of homes on the market have experienced price corrections, signaling a shift in supply vs. demand.
  • Buyer’s Options Expanded: With a 36% increase in inventory compared to last year, buyers now have a wider selection to choose from.
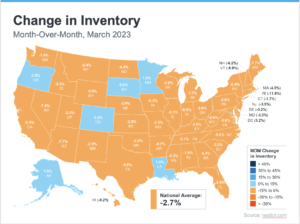
  • Regional Variations: While New York and Nevada maintain a tighter grip on their inventory, Texas is experiencing a bump in sales activity thanks to a more abundant selection.
  • Mortgage Mysteries: Curious about what drives mortgage rates? They’re more intricate than you might think. Send me a direct message for a detailed breakdown.
  • Sales Trends: The rhythm of new sales has dipped recently, but the overall pace remains consistent with last year’s figures.

Some interesting highlights: 

Understanding these trends is one thing, but distilling them into actionable insights is where true leadership shines. For a personalized analysis, slide into my DMs for a one-on-one chat.

Discover how these trends are playing out locally on my Altos link included by clicking here.

#WinTheDay by making informed decisions and keeping your clients informed and up to date.
 

Follow Up
Follow Up

Home Ownership – Single Women vs. Single Men

A trend we all need to pay attention to… have you adjusted your marketing?

A recent study from LendingTree shows that single women own 2.7 million more homes than their male counterparts, with roughly 13% of those women holding the titles to their homes, compared to 10% of men.

–

Single women who live by themselves are more likely than single men who live by themselves to own a home in 47 of 50 states.

Is The Sky Falling?

Is The Sky Falling?

Adam Smith, some 233 years ago, nailed it with the concept of supply and demand. Unfortunately, he is not here now to experience “clickbait!” If you are reading a headline like “Home Prices Are Falling,” be skeptical.

Why? In general – in most markets – it’s just not the case.  Across the US, home prices are up 2.4% to a median of $425,000 compared to last year. Are there exceptions – yes, in a few segments in a few markets – reach out to me for details, or use my Altos link to look at your specific market.

Despite significant mortgage rate increases and affordability challenges, a resilient economy combined with demographic forces of demand, there simply are not enough homes for the number of qualified buyers.

Demand did drop in 2023, yet so did supply. And Adam Smith nailed it – supply and demand forces worked. To place this in perspective, at this time in 2019, there were 822,000 homes for sale nationally: today? 546,000.

Just like Wall Street, consumers love stability and predictability. As mortgage rates stabilize and normalize, we are seeing slightly more immediate sales vs. last year. This is a leading indicator that 2024 will be stronger than 2023 from a sales perspective.

Other leading indicators? For newly homes listed, Altos is reporting a few percentage points higher on the initial list price vs. the same time a year ago, and immediate sales of those homes are slightly ahead of last year.

Price cuts? Trended over time, we see about 33%; nationally, we are at 38%, so a few percentage points higher – more than normal. I suspect these relate more to affordability than other factors.

The team over at Altos reports and updates every Monday – it’s a leading indicator – much earlier than traditional channels. I’m a fan. Win The Day!


Every Monday Matters

The National Association of REALTORS®, Lawsuits, and Doing The Right Thing

NAR, Lawsuits, and Doing The Right Thing

During the COVID lockdown, I wrote a blog titled, “Doing The Right Thing Is Always The Right Thing,” today’s unveiling of the recent lawsuit settlements brought that to mind.

I’m writing this from Tahoe, where I was part of a panel with the Realty Alliance on scaling your business. All the companies attending are the best of the best, yet some have 100 years or more of operations. You create a 100-year enterprise by always doing the right thing.

Some 20 years ago, I worked with buyers, and a co-op commission came up that was $1.00. Because I had adequately educated my buyer clients, I could show homes of any commission level—the right thing.

Today’s news released by all the major real estate news outlets summarizes some of the settlement points; only one is breaking news, in my view. The summary:

Significant

  • Redfin no longer requires agents to be NAR members.
  • Anywhere, company-owned operations no longer require NAR membership and encourage franchisees to do the same.
  • REMAX company-owned regions no longer require NAR membership and encourage franchisees to do the same.
  • Note: in most areas there is no procedure to have a hybrid membership brokerage – you are all in or all out.

Implication: Significant policy discussion at the local associations. And the decoupling of NAR, state associations, and MLS. The watch out – this could be like CPA’s not having GAP (generally accepted accounting principles). The wild wild West will not serve the consumer.

I’m a fan of the local and state associations and NAR. I see the value, the advocacy, the standards, the services like RPR, economic reports and research and so much more. More on this in another post.

I’m also a fan of freedom of choice… those who deliver the most value will not struggle to maintain members.

The Right Thing – Nothing Really New

The settlements also include the following:

  • Anywhere will prohibit their brokerages and agents from claiming buyer agent services are free and will also require agents to include the listing broker’s offer of compensation for prospective buyers’ agents as soon as possible in each active listing.
  • Agents must disclose that commissions are entirely negotiable and not set by law.
  • No minimum commission requirements
  • No technology or manual method that enables the sorting of listings by commissions offered.

The implication here? Nothing new – for over 20 years I’ve taught my agents to do the same, and executed my practice with these principles. Bringing these practices to a higher level of awareness is a good thing. Yet here is what I know, those who deliver the most value will not struggle to create thriving real estate practices.

For the vast majority of my REALTOR® colleagues – regardless of your brands position – is leadership and service not abdication. Get involved and be the change you want to see.

Doing the right thing is always the right thing!

The Case Summary:

  • Sitzer | Burnett Case
  • Moehrl Case
  • Gibson Case
  • Batton 1 & 2 Cases
  • Burton Case
  • March Case
  • QJ Team Case
  • Phillips Case
  • Nosalek Case
  • The Department of Justice / National Association of REALTORS® Case

The implication? List to last. Control your destiny. Become the best listing agent in your market.

#WinTheDay


Do The Next Right Thing!


The Economy and Housing, What’s Up?

Just received some edits from my Ph.D. friend, who is giving my textbook on the introduction to real estate economics a test drive. That got me thinking: The recession of 2023 is postponed and more likely canceled.

Moody’s Analytics has the GDP estimate for the current quarter at 3.9 percent annualized growth The Federal Reserve of Atlanta estimates growth at 5.9 percent. Either way, you slice it, healthy stats.

A point in time:

  • Unemployment is low at: 3.8%
  • Business investment: holding steady
  • Consumer spending: steady
  • Consumer sentiment: improving
  • Non-residential investment: contributed 25% of GDP growth and increasing
  • Industrial and Manufacturing: turn-around with slight improvement
  • Inflation is moderating with some disinflation for housing rent and vehicles

Housing? The challenge remains a lack of resale inventory and mortgage rates. The lack of inventory is moving homebuyers into the new home market. New residential construction is accelerating. Fun fact: NAR’s chief economist stated the resale market could absorb a 50% increase in inventory. That’s not likely to happen at current rates – thus, new home sales OR sales activity from the 10,000 Americans turning 65 each day, many of whom own their homes mortgage-free.

As seasonality picks up its pace, your buyer clients will find some opportunities between now and the end of the year.

It appears the US economy has proven more robust than the pundits thought. As inflation continues to improve and when growth remains steady, that could erase the final fears of negative growth. At the end of the day, what can we control?

  • We CANNOT control the market.
  • We CANNOT control what others think.
  • We CAN control our business process.
  • We CAN control our thoughts, behaviors, and routines.

And that’s how we win the day.

–
What's Possible?
What’s Possible?

The Real Estate Market – August 2023

For my friends in real estate and my friends that are buyers and sellers… some real estate market observations thanks to my friends over at Altos:

We all know that a change in mortgage rates reduces the real estate sales rate and vice versa. With the highest mortgage rates in 20 years, a few observations:

35% of sellers are taking a price decline from the initial sales price, which is ticking up slightly. Austin, Texas, has the highest level of price cuts, with nearly 50% of listed homes with a price cut. The lowest? Irvine, California, at 15% of homes listed.

There are 10% fewer homes on the market now than this time last year. The inventory of homes for sale tends to peak at the end of August – yet not this year with higher rates – inventory might continue to rise past normal seasonality.

Late August Observations…

  • Unsold homes ticked up this week.
  • Inventory gain week over week is the highest in a few months – and good news for your buyers that can afford to buy
  • The sales rate has slowed; part seasonality and part rates.
  • On a national basis, 365K homes are in contact right now, up a fraction vs. last week.
  • However, new pending sales this week were 63K vs. 70K last year.

As we enter into seasonality, the trend to look for – how quickly will new pending sales shrink? Will it be more significant than normal seasonality? That is the stat I’ll be watching.

One bright spot – 10,000 Americans turn 65 daily and are typically cash buyers when they downsize or move closer to family.

Look at the stats in your area – click here.

Replace fear of the unknown with curiosity.

What Happened To The Real Estate Market?

It’s that time of the month… for the real estate market update. 
 
If there were 2 slides out of the 84 from this month’s KCM updates plus 1 from Altos, which ones would I share? … you will see the 3 below, plus a link to all the slides.  
 
Do you want to attract more people to your brokerage, team, or office? Then help your team translate what all the information and data means and how to act on it. We can help, HMU.

 
Key updates for this month: 
 
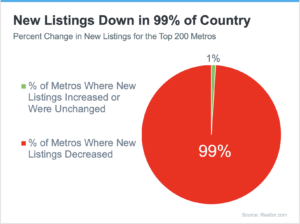
  • 247 years later, Adam Smiths’ laws of supply and demand are still working: 99% of US markets had a DECREASE in available re-sale inventory for sale. 
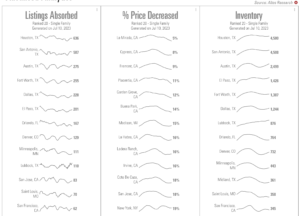
    • Let’s look at 2 markets, for the past 7 and 90-day period
    • You can type in your own market for real-time results 
  • A supply-constrained market with no relief in sight 
    • Large institutional investors have indicated no reason to sell – residential is providing higher ROI than commercial. Follow the money. 
    • Consumers are unwilling to trade a 3% mortgage for a 6%, opting instead to remodel or upgrade. 
    • New construction is growing – especially in the South – yet not nearly enough to close the gap. 
    • Freddie Mac survey: In the next 6 months = 18% of consumers indicated a desire to buy while 16% of sellers indicated a desire to sell. 
  • While affordability is always an issue consumers have never been in better financial condition 
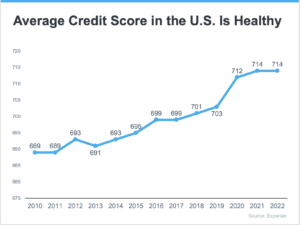
    • Average credit score the highest in 23 years – 714 Average 
    • For those applying for a mortgage: 765 is the median credit score 
  • Consumers have more access to data, and information YET lack knowledge 
    • YOU are the knowledge broker for local market activities 
    • AFTER speaking with a knowledgeable HYPER-LOCAL agent, 64.5% of homeowners were MORE likely to sell than before.
    • Creating a conversation with value-added content makes a difference – NO SECRET AGENTS! 
  • A few of the top 20 markets with the most listings sold are in Texas: Houston; San Antonio; Austin, and DFW. Some of the tightest pricing is seen in CA, with less than 12% of listings (the national average is 32%) taking a price decline in cities like La Mirada; Cypress; Fremont; Placencia & Garden Grove.
Key takeaways: 
  • Enabling Homeowners and Investors with value-added information does create listing opportunities. Especially non-owner-occupied and 1031 exchange opportunities.  
  • 16% of homeowners indicated a desire to sell in the next 6 months… that is your opportunity 
  • Sales and Rates Normalizing  – housing prices continue to show stronger growth than what was previously expected.
  • Homebuilders continue to add to supply, but years of meager homebuilding over the past business cycle means the imbalance will likely continue for some time. 
  • Seasonality has returned 
  • Prices rebounding 
Confidence is contagious, and so is a lack of confidence. There is plenty of actionable data to be confident about. 
PS: Recruiting and retention has never been more important. In all types of markets, we continue to see 10% of agents leave the industry; 10 %to 15% join the industry, and despite an 85% satisfaction rate with their broker 32% switch firms.  Need some help? Let’s chat.
—
Real Estate Inventory For Sale


Credit Scores
Credit Score Trends


Top 20 Real Estate Market Trends

Real Estate Market Update – June 26, 2023

Monday observation:

Since May of ’23, housing inventory for sale on a National basis has grown nearly 10%, giving buyers more options, while nearly 10% of sellers have taken a price reduction. Days on the market – depending on the price range – are hovering from 35 to 56 days.

What’s it mean? HMU.

Need an agent that is a hyper-local expert? I know a few on just about every continent, HMU.

See the trends in your local zip code – click here


Real Estate Market Update Week Ending 6-25-23

What’s Happening In The Real Estate Market?

What’s Happening In The Real Estate Market?

We are still in a supply-constrained market with more demand than supply, meaning in most US markets, it’s still a seller’s market.

The facts are the facts: there is not enough inventory of homes for sale to meet the demand of buyers. Check out your local market stats on this link – click here.

Why?

  1. Existing sellers will not trade a low-cost mortgage for a higher-cost one unless they have to (job change, death, divorce.) A boom for home improvement.
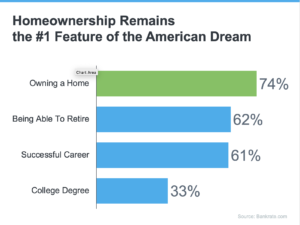
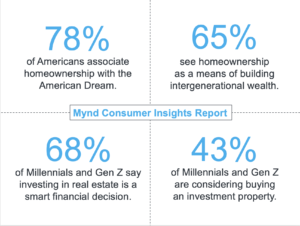
  2. Homeownership remains the #1 feature of the American dream. 74% to 78% of Americans say owning a home is still a dream.
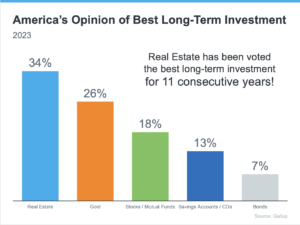
  3. More than bonds, stocks, or gold real estate has been voted the best long-term investment.

Other thoughts?

  1. Consider the median home price metric in this market is meaningless. Median prices are distorted by the mix and repeat sales. In today’s housing market, we are selling more of the less expensive homes, thus driving down the median price. It doesn’t accurately reflect the value of each house.
  2. The median sale price measures the ‘middle’ price of homes that sold, meaning that half of the homes sold for a higher price and half sold for less. For example, if more lower-priced homes have sold recently, the median sale price would decline (because the “middle” home is now a lower-priced home), even if the value of each individual home is rising.
  3. Outdated models aren’t working in this market. You’ve got to dig 4 layers deeper to be of real service to your clients and prospects.
  4. For 50 years, the 30-year mortgage rate has moved in unison with the 10-Year treasury yield. The current 3.2 is historically high. It’s reasonable to assume that the spread and mortgage rates will retreat in the second half of the year, creating more affordability and demand in an already supply-constrained market.

Outdated models aren’t working in this market. You’ve got to dig 4 layers deeper to be of real service to your clients and prospects.

How do you grow in a volatile market with unit sales down from 23% to 31%?

Attract talent and recruit!

  • We have a proven system – 10X ROI – the fundamentals are the fundamentals.
  • It’s easy to make excuses.
  • Yet we know it’s the pain of discipline vs. the pain of regret.

Let’s have NO REGRETS in our recruiting efforts this week.
TCF+ no excuses.


    Real Estate Market Update

What’s Happening In The Real Estate Market?

For my real estate friends and consumer friends, here are a few updates on the real estate market.

First, these are National stats, and as we know, real estate is hyper-local. You can check out your local zip code on this link.

In most US markets, we are still in a seller’s market… with a supply-constrained market and mortgage rates dropping below an infliction point, the spring market will be rewarding for sellers and frustrating for many buyers unless you are going into a new home build.

The challenge: inventory! There is NO indication on a National basis of any significant decline in prices. (hyper-local market exceptions occur)

Home Price Appreciation leveling out according to Case-Schiller and FHFA Top 20 Markets. Markets like Atlanta; Boston, Charlotte, and Chicago seeing solid appreciation. While markets like Seattle; San Francisco, San Diego, and Portland are creating price opportunities.

Cliff notes? We are seeing the lowest percentage of new listings on the market with a price reduction than we’ve seen for some time. Home buyers are buying at these prices. This is a supply-constrained market. Homeowners, in general, are simply unwilling to sell at all. New home builders are gaining a bigger share of housing units sold.

Check out a few of the charts below. Helpful?

Always a DM away. If you need hyper-local agents, I know one in just about every major market across the Americas, Europe, Australia, and the Philippines.